Retirement planning for individuals.

Whether you serve, run a business or care for a family, we plan around your numbers.

Retirement planning for individuals and families.

For people nearing or in retirement who want their savings to become an income they can count on, and a plan for what they leave behind.

Our approach
A smiling family of four under a tree in white blossom
  • Retirement income

    A withdrawal plan across your accounts, so your money lasts and your taxes stay low.

  • Social Security timing

    When to claim, a choice that can change what you receive over a lifetime.

  • Medicare and IRMAA

    Premiums, IRMAA surcharges and long-term care, planned before they surprise you.

  • Taxes in retirement

    Required minimum distributions, Roth conversions and the order you draw from each account.

  • Estate and legacy

    A plan for what you leave to the people you love, and how they receive it.

What every client gets.

Whichever of the three brought you here, the relationship is built the same way: one plan, one advisor who knows your situation, and the people around you kept in the loop.

  • A written plan around your numbers.

    Your investments, taxes, estate and giving in one plan, built from the same three parts every time, so no decision is made on its own.

  • Someone who knows your situation.

    You work with the advisor who built your plan, and you can text when the market has a bad week. You're never a number to us.

  • Your CPA and attorney in the loop.

    We coordinate with the people you already trust, and when you need one, we know people.

  • Reviews as your life changes.

    We meet on a schedule and in between when something touches your plan: a retirement date, a sale, a DROP exit, a new grandchild.

  • A note every month.

    What we are watching in the markets, Social Security, Medicare and the FRS, in plain words, so you hear from us before you have to ask.

  • A fee you see before you sign.

    A fee on the assets we manage, or a flat fee for planning. No annuities, no insurance, no commissions.

Client success stories.

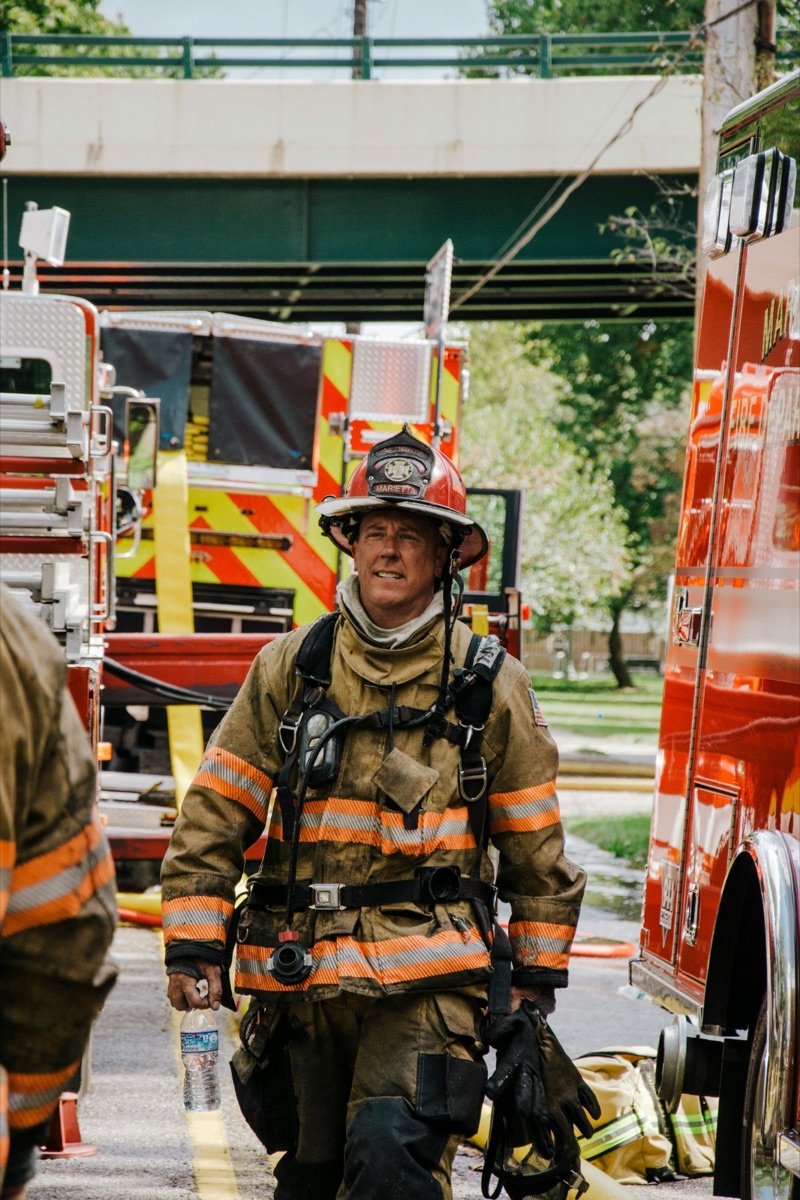
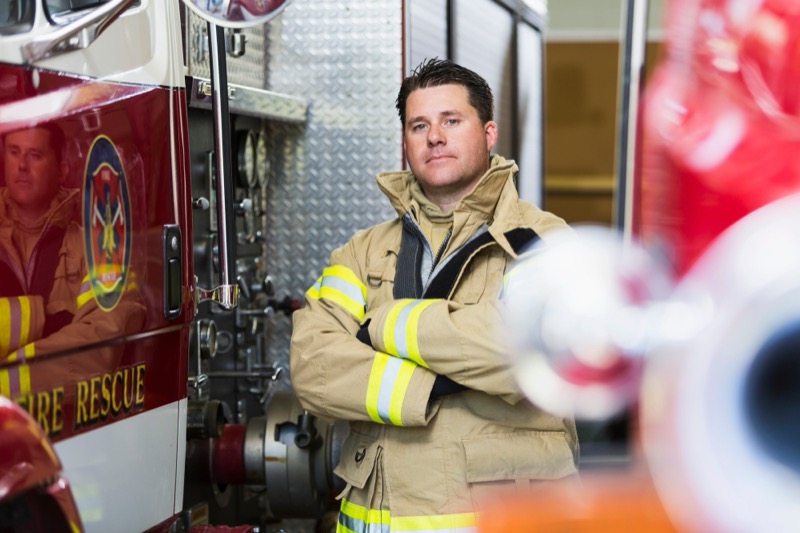
A firefighter in turnout gear, arms crossed, beside a fire engine

A DROP decision made three years early.

Situation

A firefighter with 25 years in was three years from retirement. He had entered DROP without a plan for the money, had stopped paying into his 457, and did not know whether to take the DROP balance as a check or roll it over.

Approach

We ran his pension and DROP balance against his real expenses, restarted the 457 at a level that lowered his taxes now, and set up the rollover before his last shift so the balance moved without a tax bill.

Outcome

He retired on the date he picked, with his DROP money invested and a monthly income plan that covers the gap until Social Security.
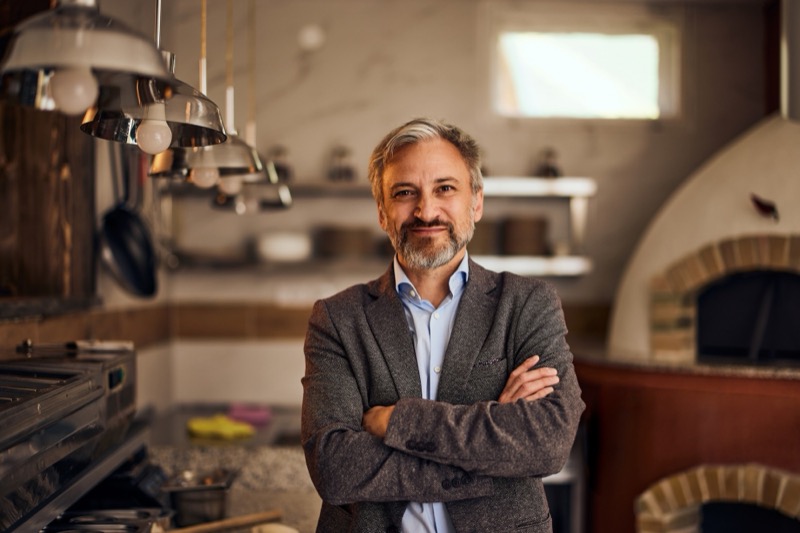
A business owner in a tweed jacket standing in his restaurant kitchen, arms crossed

A 401(k) that worked for the owner and his team.

Situation

An owner had built a profitable company and no retirement plan. His own savings sat in the business, his CPA handled taxes after the fact, and his best employees were asking about benefits.

Approach

We designed a 401(k) with profit sharing that let him put away far more for himself while giving his team a real plan, and coordinated the design with his CPA so the contributions cut his tax bill the same year.

Outcome

He now funds his own retirement outside the business, his team has a plan, and his CPA sits in on the annual review.

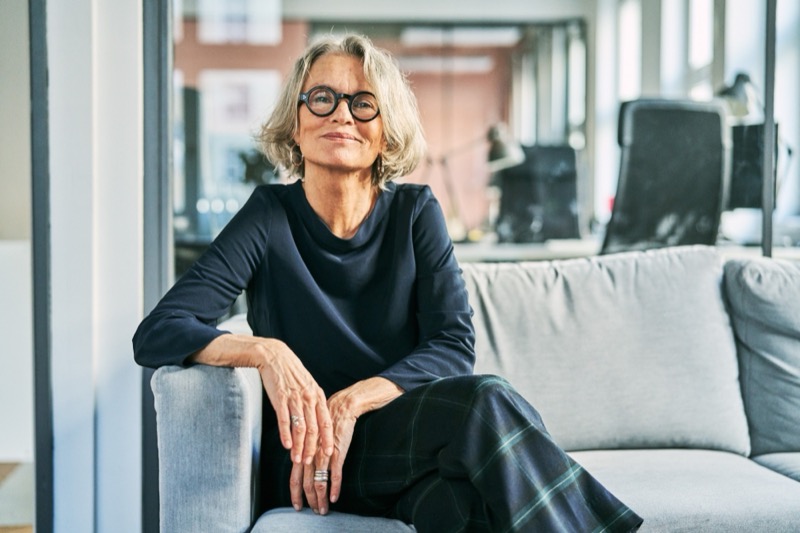
A woman with grey hair and round glasses seated on a sofa, smiling

A retirement that started with one question.

Situation

A woman a year into retirement had a pension, a small 401(k) from her last job, and a question she had been afraid to ask: was it enough? She had never worked with an advisor.

Approach

We put her income and expenses on one page, timed her Social Security claim with her pension, and moved the 401(k) into an account built to pay her monthly.

Outcome

She has a monthly income she can count on, Medicare sorted before the deadlines, and someone to call. Most of our meetings are about restaurants and movies.

These stories are hypothetical and for illustration only. They do not describe actual clients, and they are not a promise that you will see similar results. Every situation is different; outcomes depend on your circumstances, your goals, taxes and the law.

Questions people ask.

The ones that come up in almost every first conversation.

How do I know if I have enough to retire?

We put your income, expenses and timeline into one plan, then test it against an early market drop, inflation, healthcare costs and a long life. If it holds, you'll know. If it doesn't, you'll know what to change.

When should I claim Social Security?

It depends on your health, your other income, your spouse's benefit and your taxes. Claiming early, at full retirement age or later can add up to very different totals, so we compare them against your plan before you file.

What's the best retirement plan for my business?

It depends on what you earn, how many people you employ and how much you want to put away. A Solo 401(k) or SEP can suit someone working alone; a 401(k) or cash balance plan may fit a business with a team. We compare them against your numbers.

Should I choose the FRS Pension Plan or the Investment Plan?

It depends on how long you'll serve, when you want to retire and how much risk you want to carry. The Pension Plan pays a lifetime benefit set by a formula. The Investment Plan is an account you own and invest. We run both against your numbers before you choose.

What is DROP, and when should I enter it?

DROP lets Pension Plan members who reach retirement keep working for a set period while their monthly benefit builds up in an account. When you enter, how long you stay and what you do with the money when you leave all change your income and your taxes, so plan them together.

This information is general in nature and not individualized tax or investment advice. Tax rules, including RMD ages and Roth conversion treatment, are subject to change; confirm current details with a qualified professional before acting.

This information is general in nature and not individualized advice. FRS rules and benefit provisions are subject to change; confirm details with the FRS and your own advisors before making decisions.

Let's talk.

Tell us a little about where you are. We'll call you back within one business day, and the first conversation costs nothing.

(954) 652-6027charlie.thomas@farther.com8201 Peters Road, Suite 1000, Plantation, FL 33324

By sending, you agree to be contacted by Thomas Wealth Management.